
Reviewed 13 November 2026. New Zealand is in a time-sensitive licensing transition. Verify current operator status and official guidance before acting. This page is general information, not legal or financial advice.
Four questions before depositing
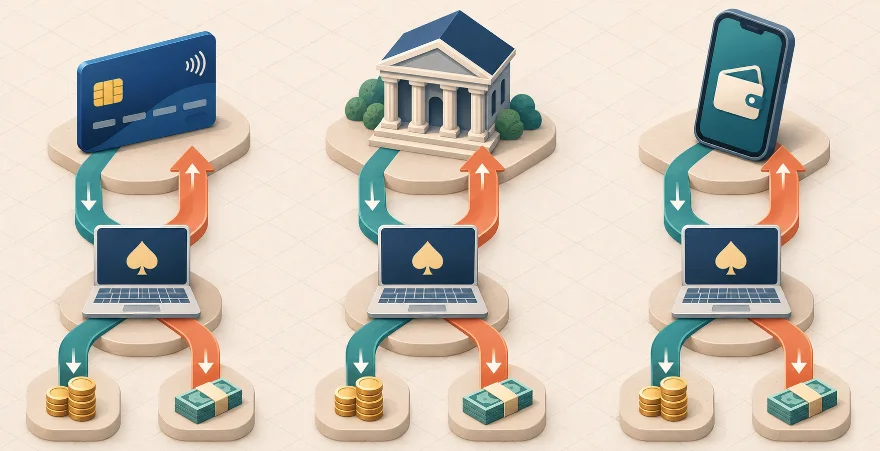
Can the method legally be used, can it receive a withdrawal, who applies currency conversion, and what records will you retain? These questions reveal more than a logo wall. A debit card, bank transfer, wallet and voucher create different evidence trails and different return paths.
Under the 2026 licensed-regime rules, credit-contract payment methods are prohibited. The rules also provide for one registered deposit method at a time, with a 24-hour wait before changing it, while operators must still allow a different withdrawal route where needed.
Deposit capability is not withdrawal capability
A wallet button may simply pass an underlying card token. A voucher may fund an account but have no mechanism to receive money. An open-banking payment initiation service sends a bank payment; it does not automatically create a push-payment withdrawal product. Always read the cashier’s withdrawal screen before depositing.
If a return to the original method is impossible, licensed operators are expected to provide an alternative path under the regulations. That does not remove KYC or payment-ownership checks.
NZD, fees and records
The regulated regime requires monetary values to be expressed in New Zealand dollars. Even so, an overseas processor or wallet can introduce conversion before the amount reaches the displayed balance. Save the quoted amount, the settled amount, the exchange rate and each fee as separate fields.
Prefer a route that gives you a durable receipt, named counterparty and transaction reference. Clear records are valuable when support, a bank or a regulator needs to reconstruct the transfer.
Quick-reference table
| Route | Can commonly receive funds? | Main check |
|---|---|---|
| Debit card | Sometimes | Is original-credit transfer supported? |
| Bank transfer | Yes | Account name and reference |
| E-wallet | Often, provider dependent | Live fees, currency and account match |
| Voucher | Often no | Confirm a separate withdrawal route |
| Cryptoasset | Yes, but not reversible | Asset, network and destination |
What to do next
- Debit cards: familiar at deposit, less simple at withdrawal
- Bank transfers: strong records, separate processing stages
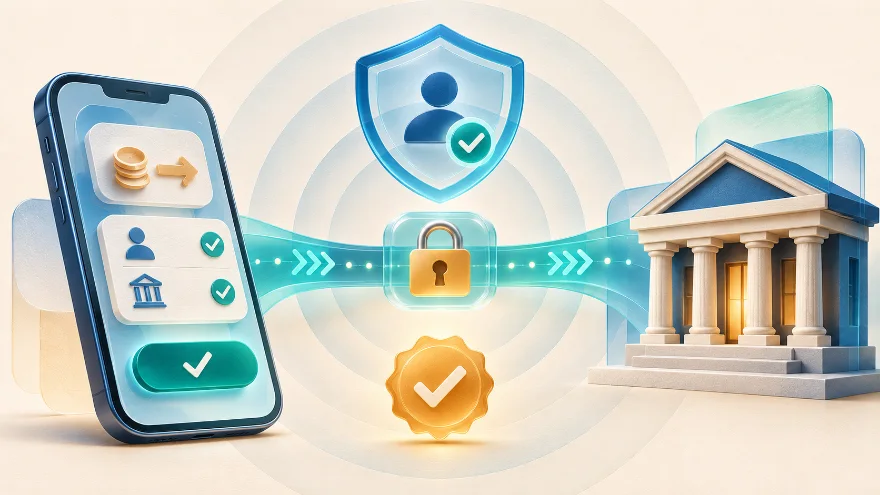
- Open banking in New Zealand is a payment rail, not a casino guarantee
- NZD conversion: compare the amount you saw with the amount settled
Frequently asked questions
Are credit cards allowed for licensed NZ online casinos?
The 2026 regulations prohibit payment methods based on a credit contract, including credit cards and buy-now-pay-later arrangements, for the licensed regime.
Is POLi the same as regulated open banking?
No. Treat legacy brand references separately from New Zealand’s regulated Consumer Data Right payment-initiation framework. Confirm the live cashier and provider.
Should I choose a method only for speed?
No. Consider withdrawal support, verification, fees, NZD conversion, security and the quality of transaction records.
Sources
- New Zealand Legislation — Online Casino Gambling Regulations 2026
- MBIE — open banking regulations now in force
- MBIE — uptake of the Consumer Data Right
- MBIE — Consumer Data Right standards
Payout Path NZ includes labelled partner advertising alongside its editorial guides. If gambling is causing concern, call Gambling Helpline on 0800 654 655 or text 8006.